Justin Keats | New York Homebuyer Insurance Specialist
NYC Condos & Co-ops • Brooklyn Brownstones • Long Island Homes
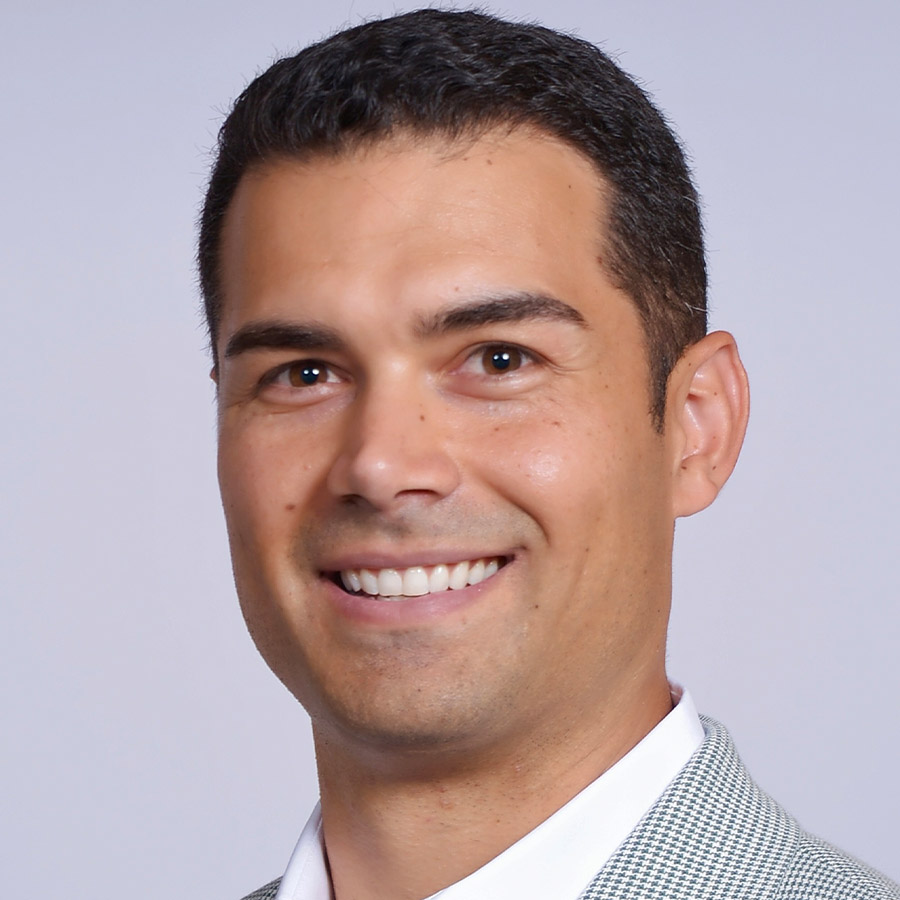
Justin joined Keats Insurance in 2014 and specializes in working with homebuyers, successful individuals and families who want a more thoughtful approach to protecting their homes, assets and lifestyle. His clients range from NYC condo and co-op buyers and Brooklyn brownstone owners to homeowners throughout Long Island, Scarsdale and Westchester, including high-net-worth and private client households with more complex insurance needs.
A large part of Justin’s practice is built around the home purchase and closing process. He works closely with buyers, realtors, mortgage professionals and attorneys to keep the insurance piece moving from contract through closing, while helping clients understand the coverage that matters. As an independent broker, Justin has access to a broad range of standard, high-value and private client insurance markets, including preferred carrier programs and pricing opportunities when available.
Before becoming a broker, Justin worked in claims with GEICO, giving him a perspective that continues to shape how he advises clients today. He believes insurance should be evaluated based on how it will respond when something actually goes wrong, not simply on the lowest premium.
A graduate of The Ohio State University, Justin has continued his insurance education throughout his career, including earning the Commercial Lines Coverage Specialist (CLCS) designation and completing the Dale Carnegie program. His approach is simple: listen first, explain the options clearly and give clients the information they need to make a good decision.
Whether the need is a Manhattan condo, Brooklyn brownstone, Long Island or Westchester home, private client portfolio, auto, umbrella, jewelry or business insurance, Justin’s goal is to make the insurance process feel organized, proactive and seamless.
In contract? Send the property address and closing date to JustinKeats@KeatsAgency.com and we’ll take it from there.
Justin's Specialties
Long Island Home Insurance
Buying on Long Island comes with its own insurance challenges.
From older North Shore homes to coastal properties, new construction and high-value estates, Long Island homes can be very different from one another.
The insurance process can be just as different.
We help buyers identify potential underwriting issues early, compare the right insurance markets and keep the insurance piece moving from contract through closing.
What we help with
Some of the most common Long Island considerations include:
- Coastal and waterfront exposure
- Flood zones and flood insurance
- Wind and hurricane deductibles
- Roof age and condition
- Older electrical, plumbing and heating systems
- Oil tanks
- Replacement cost on larger or unique homes
- Pools, detached structures and property features
- Renovations planned after closing
- High-value homes and private client coverage
- Auto, umbrella, jewelry and other personal insurance needs
- Carrier inspections and underwriting requirements
- Lender requests and changing closing dates
The home matters. So does the insurance market.
Two homes with the same purchase price may need completely different insurance solutions.
Location, distance to the water, age of the home, construction, replacement cost and prior updates can all affect which insurance companies are willing to write the property and how they price it.
As an independent broker, we can look across a range of standard and private client carriers to find the right fit. For higher-value households, that can also mean access to broader coverage, higher limits and carrier programs that may not be available through a typical homeowners policy.
Catching issues before they become closing issues
A roof, an oil tank, a coastal location or an upcoming renovation may not sound like a major concern until an insurance company starts asking questions.
We would rather find those issues early.
Once the contract is signed, we can review the property, gather the information carriers need, and work with the lender so there are fewer surprises as the closing gets closer.
From contract to closing
Our job is to make the insurance piece feel organized, proactive and easy to manage.
And once the closing is complete, we want the coverage to make sense for the home and the household you are actually protecting.
In contract on Long Island? Send us the property address and expected closing date. We’ll take it from there.
Brooklyn Brownstone Insurance
Brownstones come with character. They also come with different insurance challenges.
Brooklyn brownstones and row homes are often defined by the details that make them special: original woodwork, plaster, masonry, fireplaces, staircases, moldings and historic finishes.
Those same features can also make them more complicated and expensive to repair or rebuild after a loss. We help buyers make sure the insurance reflects the home they are actually purchasing, not just the purchase price or a standard replacement-cost estimate.
What we look at
With Brooklyn brownstones and row homes, some of the biggest considerations can include:
- Original architectural details and finishes
- Higher reconstruction costs
- Shared or closely connected walls
- Limited construction access
- Tight streets and staging challenges
- Older masonry, roofing, plumbing and electrical systems
- One-, two- and three-family occupancy
- Rental units
- Renovations before or after moving in
- Water damage and sewer backup
- Ordinance and law requirements
- Personal liability and umbrella coverage
Rebuilding in Brooklyn is different
Replacing part of a brownstone is not always as simple as rebuilding a typical detached home. Row-house construction, neighboring properties, limited access, historic materials and the cost of working in the boroughs can all affect what it takes to restore a home after a major loss.
That is why we pay close attention to replacement cost and how the policy would actually respond, not simply what the lender requires for closing.
Planning renovations?
If you are buying a brownstone with plans to renovate, it is important to discuss that before the policy is placed. A home being occupied as-is can require a very different insurance solution than one undergoing significant construction immediately after closing.
From contract to closing
We work with the buyer, realtor, attorney and lender to get the insurance handled early and keep things moving toward closing.
Our goal is to make sure the policy works for the closing, but more importantly, for the home you are actually buying.
Buying a Brooklyn brownstone or row home? Send us the address and expected closing date. We’ll take it from there.
NYC Condo & Co-op Insurance
Insurance that keeps up with the closing.
Buying a condo or co-op in New York often means coordinating with more than just the lender.
There may be board requirements, managing agent requests, building insurance requirements and closing dates that move with very little notice.
We help buyers, realtors, attorneys and lenders keep the insurance piece organized and ready as the transaction moves toward closing.
What we help with
Every building and transaction is a little different. We regularly help buyers navigate:
- Condo vs. co-op coverage
- Board insurance requirements
- Managing agent and management company requirements
- Building master policy requirements
- Lender insurance requirements
- Insurance binders and mortgagee clauses
- Changes to closing dates
- Last-minute requests before closing
- Dwelling and improvements coverage
- Water backup and water damage
- Loss assessment
- Additional living expenses
- Personal liability and umbrella coverage
- Jewelry, art and other valuables
More moving parts than a typical home purchase
A condo or co-op closing can involve the buyer, attorney, lender, realtor, managing agent and building management all asking for slightly different documentation.
Sometimes the closing date changes. Sometimes the lender needs revised evidence. Sometimes the managing agent has requirements that do not come up until late in the process.
Our job is to stay ahead of those details and help keep insurance from becoming the thing that slows the closing down.
More than just checking a box for the bank
The lender may be focused on what is required to close.
We are also looking at what the building covers, what belongs to you and how the policy should respond after you move in.
From contract to closing
The best time to bring us in is once the contract is signed.
From there, we can review the property, coordinate with the parties involved and adjust as the closing develops.
In contract on a NYC condo or co-op? Send us the property address and expected closing date. We’ll take it from there.
Team Justin


Reviews
“Justin was patient, thorough, and found us better coverage for less than we expected.”
“Keats Agency makes everything so easy — highly recommend Justin for any business policy.”
→ Want to see more reviews? Read all Keats Insurance reviews on Google
Get A Quote
Request a custom quote — Justin will follow up with you directly.
Getting to Know Justin
- 11 years of experience as an insurance producer
- 2 years as a claims adjuster with GEICO
- Licensed in NY, NJ, CT, and PA
- Specializing in high-value home, coop, condo, auto, brownstones, and small business insurance
What Justin Can Help With
Home • Condo • Coop • Brownstones • Auto • Business Owners • Workers Comp • General Liability • Umbrella • Flood • Life • Builders Risk
Why Work With Justin